Ocado’s share price raced to hit a 13-month high this week, as Morgan Stanley became the latest bank to re-evaluate the retail tech firm’s prospects.
Shares in Ocado climbed 15% in the week to reach 348p, after a note from the bank’s analysts upgraded the previously troubled stock from a target price of 170p to 300p. The upgrade meant Morgan Stanley now recommends investors maintain holdings in the company rather than reduce their exposure.
The stock’s price has risen 58% over the past six months, putting it on a high last seen in August 2025.
The City’s re-evaluation of Ocado has been driven by a trickle of new deals around the world – and the growing distance between Ocado and the high-profile cancellations of warehouse contracts with North American chains Kroger and Sobeys in late 2025 and early 2026.
Investor jitters over the company’s succession plan have likewise settled, as CEO Tim Steiner held onto his seat in a June 2026 boardroom battle. He will remain as CEO until the end of FY2028.
“Much of the negative news flow is now in the rear-view mirror,” said Morgan Stanley analyst Ed Young.
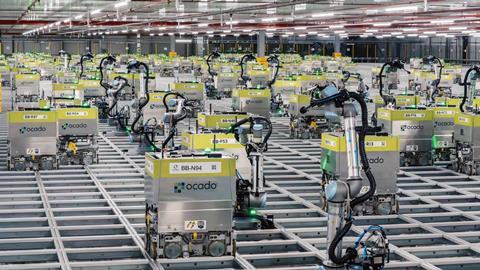
Kroger and Sobeys have already closed some of their automated warehouses (CFCs), and other customers including Lotte and Aegon have delayed launches. That means the bad news for investors has largely played out, according to Young, with the focus now on “green shoots” on the horizon.
This week, it opened a second CFC with Aeon to support the Japanese supermarket’s online grocery business, which grew sales 70% this year.
In July, Ocado signed a new CFC contract with Nemlig, Denmark’s largest online grocer.
The launch of Ocado’s first Korean CFC with supermarket Lotte lifted sentiment in August, coinciding with an JP Morgan upgrade to 290p. Analyst Marcus Diebel said at the time he “liked the [Ocado] story” and the stock rating did not reflect the value of current contracts already signed, let alone anything new.
Young added other positive sector signs included the recovery of revenues at US rival Autostore and the upward trajectory of Amazon’s capex spend in automation.
“[These are] an important industry read-across. Whether Ocado can capture meaningful demand for its micro CFC offering (store-based-automation) is still an unknown.
“Ocado is a ‘show me’ story, with a need to prove to investors whether existing CFCs are cash generative enough to support a large research & development cost base.”
No comments yet