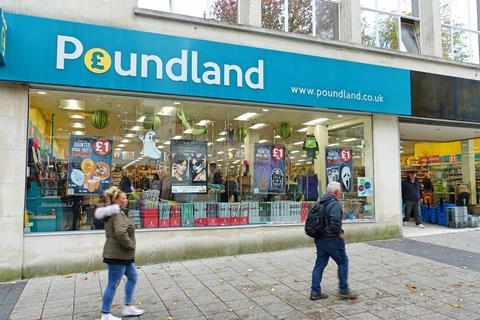
The future of Poundland and the jobs of 12,000 staff are in grave jeopardy as insolvency experts have been lined up to take charge of the discount chain following a deterioration in the relationship of its owners and management team.
A notice of intention to appoint consultancy firm AlixPartners as administrator has been filed with the courts this afternoon.
Poundland MD Barry Williams said today that “despite enormous efforts”, and a two-month formal sale process, it had not been possible to identify an acceptable offer for the business as a whole.
“The process has, however, attracted several established retail operators who have made formal offers. Collectively these cover a significant part of the business, and we believe offer the best available prospects for shareholders, creditors and to preserve jobs.”
The filing of the NOI will provide breathing room for 10 days while the company works with its advisors to put together a last-minute rescue deal or break up the business and salvage as many jobs as possible. The likes of Poundstretcher, The Range and discounters Aldi and Lidl, and other retailers, are understood to be circling in the hopes of picking up swathes of the chain’s 600 stores.
“We recognise any sale process creates uncertainty and particularly when set against a challenging UK economic environment,” Williams said. “We thank all stakeholders, and, in particular, our people for their support during this period.
“To bring stability, we have today filed a notice of intention to appoint representatives of AlixPartners as administrators to the business.
“Our stores remain open as normal and we thank our staff, suppliers and customers for their continued support.”
There remains a slim chance a solvent solution could be found to avoid a total collapse, but this relies on a change of heart from owner Gordon Brothers, which has already turned down an offer, backed by Poundland’s exec team, from Irish real estate firm Martin Property Group.
Gordon Brothers picked up the struggling discount chain from former owner Pepco for just £1 last year, essentially also buying £30m in secured debt. The US investment firm is reportedly unwilling to sell Poundland as a whole unless it recoups the £30m shareholder loan up front.
This week, three restructuring experts (Andrew Kirkpatrick, Stephen Welch and Dominic Young) appointed as Poundland directors just 14 days ago to steer the business through an emergency sale process, resigned in protest over Gordon Brothers’ actions to push for administration to recoup its money.
A letter sent by Poundland boss Barry Williams to employees – first revealed by The Times on Tuesday – expressed disappointment that Gordon Brothers rejected the offer from the property group.
He said the situation was “unexpected, unwanted and wholly avoidable”.
Williams added Gordon Brothers also made the decision to withhold funding needed to keep running day-to-day operations.
“I’m disappointed to have to tell you that Gordon Brothers have restricted access to funds that we would in normal circumstances expect to access fully under our existing loan agreement,” the letter said.
And now major suppliers have started to distance themselves from Poundland over worries the company will not be able to pay its bills. Sky News reported today that the chain’s biggest suppliers were taking steps to restrict deliveries to stores.
The crisis has attracted the attention of government with business secretary Jonathan Reynolds instructing his advisors to “establish the facts” of the potential collapse. The situation has dominated the media this week and threatened to overshadow yesterday’s budget. Hundreds of jobs in prime minister Andy Burnham’s Makerfield constituency also hang in the balance at a Poundland distribution centre.
Williams has insisted momentum for a turnaround has been taking shape at the business in recent months.
His memo to staff this week said: “As you all know, our sales are strong and our recovery is taking root. This business simply does not deserve to go into any kind of administration.”
The Poundland managing director added the offer from Martin Property Group was a “fully funded, ready to go bid that would have kept the business intact and able to continue the remarkable progress we’ve made”.
A Gordon Brothers spokesperson said: “While Martin Property Group had been identified as the preferred bidder by Poundland’s management team, attention must now turn to other active bids.
“As well as interest from buyers for the whole business, the sale process has also surfaced a number of formal and indicative offers for significant viable parts of the business from established retail operators. These options will now be objectively evaluated, with a view to minimising uncertainty for Poundland’s people and all relevant stakeholders.”
AlixPartners declined to comment.
No comments yet