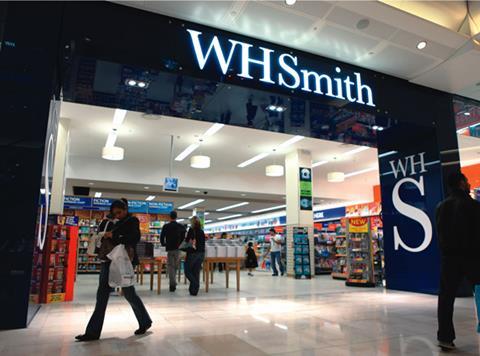
WH Smith shareholders shrugged off another lackluster trading update last week, after the embattled travel retailer posted profits at the very bottom of guidance it had previously downgraded.
An update to investors revealed the retailer had made £75m in pre-tax profits in 2026, having lowered its forecasts by £15m to £75m to £90m in June.
But while shares initially dropped 4% in reaction to the news as some shareholders sold off, others bet on WH Smith’s oingoing turnaround, and shares ended the week 1% higher than they had started.
Optimism came in part from the company’s growing revenues and a substantial fall in its debt levels, though for many the bad news had simply been priced in: WH Smith’s share price has already fallen 44% over the past 12 months.
Revenues grew 4% in the final quarter of the year, with UK revenues up 7%. But WH Smith ascribed its fall in profits to increased promotional activity and lower marketing spend by brands, meaning the jump in revenues came in part at the cost of its own profits.
“Revenues might be edging higher, it’s margin trouble that’s creating the problem, as promotions and inflation-related costs bite,” said Freetrade investment writer Duncan Ferris.
“The gap between total and like-for-like revenue growth shows most of WH Smith’s gains are coming from opening new locations, rather than improving sales in existing stores. In conjunction with the impact of promotional activity on margins, it would seem WH Smith is having to spend money to make money.”
Investors’ main concern has been over the retailer’s US division’s performance – especially following an accounting scandal that wiped £40m off the division’s profits in August last year.
WH Smith is attempting to exit its low-margin resorts business on the continent, leaving it to focus on its airport retail operations. But airline like-for-like sales dropped by 2% in the US in Q4, making the division “still a concern”, according to Peel Hunt analyst Jonathan Pritchard.
“Passenger numbers continue to be under pressure, and it has been a weak summer for air travel,” he said.
“Management does not see much of a pick up in underlying demand occurring soon, so the risk is going to remain to the downside of US air numbers.”
But the news that WH Smith has managed to slash its debt burden by around £170m to roughly £325m went some way toward improving investors’ mood. A substantial proportion of that money came from the company’s £103m equity raise earlier in the summer which diluted existing shareholdings, however.
Market commentators found little grounds for an immediate improvement for the stock.
“WH Smith is having a hard time convincing the market its problems can be solved quickly,” said AJ Bell head of markets Dan Coatsworth.
“North America has been the worry point and fourth quarter revenue growth has slowed versus the previous three months. On a like-for-like basis, Q4 sales have fallen for the region, which is not what WH Smith needs to win over investors.”
The rebound in oil prices as the Middle East conflict flared back up – crude oil soared back above $100 per barrel in September for the first time since May – will only exacerbate the retailer’s woes, he added.
“WH Smith talks about ‘good progress’ on its transformation strategy, but the latest trading figures suggest that its journey to get back on top could be a lengthy one.”

No comments yet