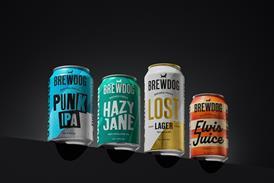
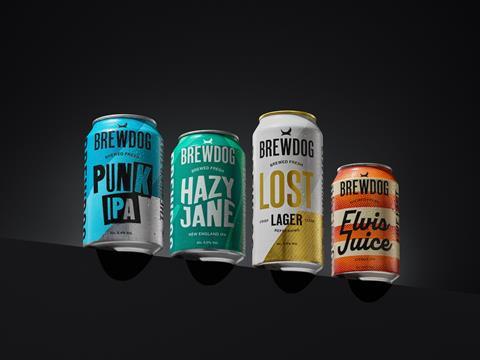
Unsecured creditors owed £190m following the collapse of BrewDog are set to receive less than one penny in the pound, an administrator’s progress report for the stricken business has revealed.
Meanwhile, unsecured creditors of BrewDog’s bar business owed over £200m, and staff owed wages and unpaid holiday totalling almost £500k, will not receive a payout of any kind.
Administrators at AlixPartners wrote there were “insufficient funds” to pay all of BrewDog’s creditors, after parts of the UK business were sold to US fmcg company Tilray Brands for just £33m in March.
BrewDog’s principal lender HSBC faces a shortfall of around £17m on the £31.2m it was owed by BrewDog plc, while its Equipment Finance arm is set to miss out on a further £523k, according to the report by AlixPartners.
TSG, the private equity firm that bankrolled much of BrewDog’s growth after taking a 22% stake in the business in 2018, will receive no return on the £27.6m it is owed by the business.
Meanwhile, HMRC will also receive none of the £2.4m in unpaid VAT, employee National Insurance contributions and PAYE deductions owed to it by BrewDog’s retail arm.
BrewDog appointed advisors to run an accelerated sales process in mid-February, after TSG elected to withdraw further funding from the business.
Tilray Brands quickly struck a deal to acquire certain parts of the UK business, before subsequently also buying up parts of BrewDog’s International arm later in March.
The cut-price deal resulted in almost 500 BrewDog staff losing their jobs after the closure of much of its UK bar estate. Meanwhile, former retail shareholders which had backed the business to the tune of £80m, were left empty-handed.
Founder James Watt was also ousted as a director, having previously stood down as CEO in 2024.
No comments yet