The US has a reputation as a graveyard for UK brands. What can we learn from the success stories?
For many Brits, the allure of the American dream has turned out to be a nightmare. Oasis and Robbie Williams failed to make a splash across the pond during their 1990s heyday, while Geordie golden boys Ant & Dec’s attempts to crack the US were met with yawning indifference.
Scores of British retail chains have fared no better, epitomised by the infamous humbling of Tesco in 2013. The UK’s biggest retailer fled American shores after failing to make headway with its Fresh & Easy concept, costing it billions of dollars in losses.
Despite these horror stories, the US continues to be the holy grail for the brightest and best on the UK food and drink scene. In recent years, numerous British brands have made headway in the land of the free in a manner the Gallagher brothers could only dream of. So, what are these brands getting right? What are the key differences to consider when it comes to dealing with our American cousins? And what pitfalls do they face?
Bigger market
“The US is the single biggest prize for a consumer goods brand,” says David Milner, whose US successes include Tyrrells and St Pierre. “There’s 345 million people. They’ve got lots of money, and they love something new. But it’s also the most competitive market in the world and most people fail because they don’t realise how expensive it’s going to be and how much time it’s going to soak up.”
Soft drinks brand Trip has embraced that competition – and is winning. Earlier this year, it took home the Grocer Gold award for Exporter of the Year after a monumental American breakthrough.
The challenger registered a remarkable 1,500% growth rate in the market in 2025, building distribution across every US state and becoming the largest UK-owned non-alcoholic beverage brand in the country. New listings this year with Costco, Walmart and, most recently, Albertsons put the brand in more than 20,000 doors (the US equivalent of stores). Co-founder Olivia Ferdi expects US sales to reach $150m in 2027.
“When we launched Trip, we always knew we wanted to have a global impact,” she says. “Our mission is to help a billion people find calm – and to be a global household name you need to succeed in the US.”
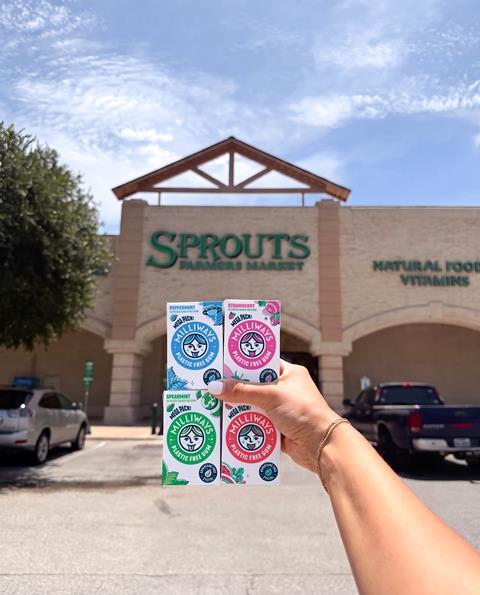
Trip’s progress may be the most eye-catching among the latest generation of UK grocery startup brands, but there are similar stories in progress at the Huel, Misfits, Milliways, Doughlicious and Moth brands, to name just a handful.
Misfits co-founder Henry Sether jumped on the US opportunity when the snack disruptor struggled to make headway in its home market. He found a surprising gap in the US for indulgent protein bars and was convinced America provided Misfits with a better fit than the UK.
“Everyone said: ‘Don’t do it, it’s where good brands go to die.’ But my view is it’s difficult to build a brand anywhere, and arguably the UK is even harder because of the size of prize, the competitive landscape and the smaller total addressable market,” he says.
Today, 90% of Misfits’ sales come from the US, and Sether expects to turn over $25m in the country this year before doubling and doubling again.
With a population five times the size of the UK, the US grocery market is worth a whopping $1.1tn (£813bn) a year, compared with about £220bn here, according to NIQ. This scale means dramatically more fragmentation to navigate across a vast landscape, argues David Wilson, who was tasked with launching Quorn in the US in 2000. Wilson went on to form Green Seed, a consultancy advising the likes of St Pierre, Pukka Herbs and Maldon Salt on getting a foothold in the country. He points out that even a narrow, regional launch in the US presents an outsized opportunity.
This fact is not lost on Milliways founder Tom Raviv, who brought his plastic-free chewing gum brand to the US in late 2024. “The reality is you can win one listing in the US and it could be bigger than your entire UK business,” he says.
In its home market, Milliways is a minnow battling for space against the whale that is Mars Wrigley in a £400m category. Compare that to the US, where the sub-sector of natural gum is worth $300m alone in a wider $4bn category, and Raviv sees no reason why his challenger can’t one day generate sales topping $100m, which would be close to impossible domestically.
Winning retail listings, however, is only the beginning.
“The number one difference with the UK market is it’s unbelievably easy to get distribution in the US and unbelievably hard to get pull off the shelf, for the simple reason stores are much bigger and carry a far larger number of SKUs,” says Anthony Fletcher, former CEO of Graze. “Many UK founders feel they’ve got traction in the US because they’re getting all those doors but are then disappointed with how fast their product turns.”
Graze established a nationwide distribution and logistics network under Fletcher, only for Unilever to pull the plug on the snack brand’s American adventure shortly after acquiring the business in 2019.
Katie Birrell, managing director of the Food & Drink Exporters Association, agrees it’s a “very noisy market” and “not for the faint-hearted”. But she also says expectations for rate of sale are lower as a result.
For Moth co-founder Rob Wallis, the big differences in seasonality determine which RTD cocktails will go down best in the states of Illinois, California and Florida, where the brand currently has a presence. “Winter in Chicago is not the same deal as in LA. There are icebergs on Lake Michigan versus 300 days of sunshine in California,” he points out.
Moth is also forced to navigate a patchwork of state-by-state alcohol regulations as dictated by the 21st Amendment following the end of Prohibition. “The list of differences with the UK is much longer than the list of similarities. The language is a red herring,” Wallis says. “You go in with all these assumptions, and you’re wrong. In the UK, about 90% of RTD purchased is drunk within two hours. Someone walks into a Sainsbury’s Local, picks up a cold can from the fridge and drinks it on the way to wherever. Some of those steps, you’d be arrested for in the US.”
Weighing up expenses
Brands entering the US market also need to go in with their eyes wide open to the different expectations around spending money. The layers of cost from import duties, freight charges, logistics, distributor and broker agreements all stack on top of payments to supermarket partners, not to mention Donald Trump’s tariffs.
“There’s a whole bunch of fees that if you go in blindly, you can all of a sudden be losing money on every transaction,” Raviv warns. “You get charged to run a discount, you get charged to run a promotion, there’s a charge by the distributor and the retailer for shelf-edge labels, and then there are slotting fees. There’s a charge for everything.”
Having the right advisers to help navigate how the market works, as well as building in extra margin, can make or break a challenger, he adds.
Slotting fees to secure space on shelf commonly run from $250 to $1,000 per item per store and can reach up to $250k for placement across a full regional chain in a high-demand market, according to Wilson. For brands used to being protected by the Groceries Code Adjudicator in the UK, which places restrictions on supermarket listing fees, the US approach can come as a bit of a shock.
Paying to support promotions will be less of a surprise, with roughly a third of all fmcg sales in the UK being done on a deal. But the devil is in the detail, as using coupons is embedded in US culture, with more than 90% of shoppers clipping them. Wilson says suppliers are expected to fund bogof offers, off-invoice discounts and coupons as a standard cost of doing business, not just an occasional lever.
Two additional layers easily overlooked by UK suppliers are integral to the US market, with both distributors and brokers acting as gatekeepers for getting products on the shelves in the first place.
The two dominant wholesalers any UK brands will likely deal with are UNFI and KeHE. The former serves about 30,000 retail locations and reports $30bn-plus in annual revenues, while the latter is smaller at around $8bn in sales but still serving the same number of stores. Crucially, KeHE is the leading distributor for the natural and specialty channel, including Whole Foods Market and Sprouts Farmers Market, which most UK players will have in their sights.
A single distribution agreement can open hundreds of doors without the need to build a US sales force on the ground or worry about warehousing and logistics, Wilson adds. But it will come at the expense of a 10% to 30% margin. Similarly, brokers will take 5% in commissions and in return manage relationships with the likes of Walmart, Target and Albertsons.
The high dollar versus the pound and a wealthy consumer means premium products can fetch premium prices in the States, which is needed if a UK brand is to absorb the cost stack.
Birrell, who spent 16 years leading overseas sales at Nairn’s Oatcakes, including a US launch in the 1990s, warns suppliers need to be patient and prepared for overinvestment for the first few years in the country. “There are different ways to cut it, but if you want to be the next Trip in the US, and really make it work, you’ve got to have the stomach for investing,” she says.
Trip raised $40m late last year to support its rapid rise in the US, but a whole slew of disruptors have secured cash in 2026 to fund growth plans, including Moth (£11m), functional coffee and matcha startup Reformed (£17m) and Michelin-star curry sauces maker Gymkhana (£6.3m).
Ferdi notes every single line of Trip’s P&L is greater in the US, but says it’s proportional to the greater scale and opportunity. She highlights that the biggest incumbent competitors in gala categories, such as soft drinks, would likely be raising hundreds of millions of dollars to get to $500m in sales.
“It doesn’t mean you have to raise $200m, but you have to be totally aware it’s commonplace in the market,” she says. “We take even more care to really sweat every single dollar we spend, whether it’s on logistics, slotting or marketing, so we can invest in things that give the consumer value, which is an amazing product and an amazing brand that they love.”
Finally, the Trump factor cannot be ignored. Tariffs imposed on UK businesses in April 2025 have already had an impact on export figures to the US, which fell by 9% in the second half of 2025 and by 28% year on year to £530m in Q1 2026, according to the latest FDF trade snapshot. exports to the US – which is our third-largest overseas market after Ireland and France – had been growing steadily since 2021, from £1.97bn to £2.77bn in 2025. But tariffs are already reshaping the picture and should be a live variable in any US launch plan, warns Wilson.
“The US gave me more sleepless nights than any other market in the world”
Health & wellness
The UK brands currently making headway in the US are all on the right side of prevailing consumer trends, with premium, functional and wellness products in big demand, especially as the Make America Healthy Again agenda in the White House and the rapid uptake of GLP-1s put a greater focus on the nutritional value of food and cleaner labels. And the channels most open to these brands also happen to be the ones growing the fastest.
The US natural and organic products market has swollen in size by 545% since 2001, reaching $342bn in 2025 and far outpacing growth in conventional groceries, according to the latest report produced by SPINS. The speciality food industry, led by the likes of Whole Foods and Sprouts, has also ballooned from $178bn in 2021, to more than $230bn in 2025.
“GLP-1s have not just had a huge impact on the amount consumers are eating but on the whole public discourse around what they’re eating,” says OC&C global managing partner Will Hayllar. “It’s driving a series of wider questions about what’s in lots of mainstream American food. And the reality is much of it’s pretty bad relative to European standards on clean label, quality of ingredients and nutritional profile. Suddenly there’s heightened demand from consumers and from retailers looking to respond, rejuvenate and regenerate big parts of the store fixtures.”
This has shifted the balance of power away from the traditional big CPG players towards fast-moving, disruptive brands – with private label also starting to gain market share. The likes of Kraft Heinz, Pepsico and General Mills are all struggling to adapt, shedding volumes consistently quarter over quarter in North America. NIQ data shows US grocery stores shifted 8.4 billion fewer units in the 52 weeks to 15 August 2026 than they did in the same period four years previously.
And it’s leading to the birth of categories that didn’t exist just a few years ago.
Four disruptors to watch in the US
Gymkhana Fine Foods
Founder Gulrez Arora, who spent 10 years building brands at Mars, set his sets on the US market from day one. The high-end Indian sauces spin-off from two Michelin-starred restaurant Gymkhana launched exclusively with Whole Foods Market across all 500 stores earlier this year, and has since rolled out across Sprouts Farmers Market after capitalising on the 2025 Las Vegas opening of its namesake restaurant partner.
Reformed
After building a sales run rate of £52m in just two years, the functional coffee and matcha brand is set to replicate its UK DTC subscription model success Stateside this autumn. The drinks, boosted with collagen, creatine and vitamins, are bang on trend for US consumers and founders Neil Saada and Neil Marrakchi have ambitions to compete with the likes of Nespresso in the long term.
All Things
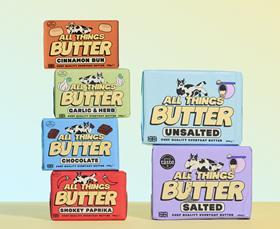
Thomas Straker’s viral butter brand is gearing up for a US retail debut later this month. The launch will coincide with the opening of the British chef’s new restaurant in New York. The dairy challenger secured a multimillion-pound investment this year to keep up with the monumental demand for its cottage cheese in the UK and pave the way to take its butter across the pond.
Dirtea
Taking a leaf out of Trip’s playbook, Dirtea’s organic mushroom teas and coffees aim to offer consumers a dose of calm. The supplement startup pipped Trip as the UK’s fastest-growing food and drink brand in this year’s Alantra Fast 50 ranking. And it is now beginning to take on the US, landing on the shelves of 650 The Vitamin Shoppe stores across 46 states.
“Unusually, Trip is a category creator in the US, whereas UK brands typically enter only once a category is already established,” Ferdi says. “Calming beverages is the fastest-growing functional drinks category. This is ahead of gut health and hydration, both of which are multibillion-dollar categories.”
She links it to mental health, stress and anxiety, which are three of the top five US health concerns. “It’s clear to US retailers that calm [as a category] is the next energy drinks, and they’re supporting that category growth.”
With a retail landscape of more than 300,000 stores across mainstream, convenience, warehouse clubs such as Costco, specialty shops, dollar outlets and scores of independent delis, UK brands with US aspirations are spoiled for choice. But Wilson advises a national launch strategy rarely works out of the gate, with a regional or channel-specific entry a more realistic and cost-effective starting point.
“You’ve got to walk before you run. You can start in 50 or 150 stores. If it doesn’t go that well and you need to change your packaging or formulation, you could start with another 150 stores somewhere else, and you haven’t burnt your bridges in the same way as if you mess up a launch in Sainsbury’s or Tesco,” he says.
Trip added 15,000 doors in 2025, but it still followed the strategy of starting small and targeted. It launched in high-end accounts such as Soho House locations and the LA mecca of wellness Erewhon at the tail end of 2024, before rolling out further in California across the specialty channel in the likes of Bristol Farms and Mother’s Market. Whole Foods and Sprouts soon followed, along with regional grocers such as H-E-B and Wegmans and then mass chains Target and Walmart.
“The rate at which retailers respond to success in the US is amazing,” Ferdi says. “On multiple occasions, we’ve launched in a few hundred doors and will do well for three or four months, and they’ll just roll us up nationwide in thousands of stores very quickly.”
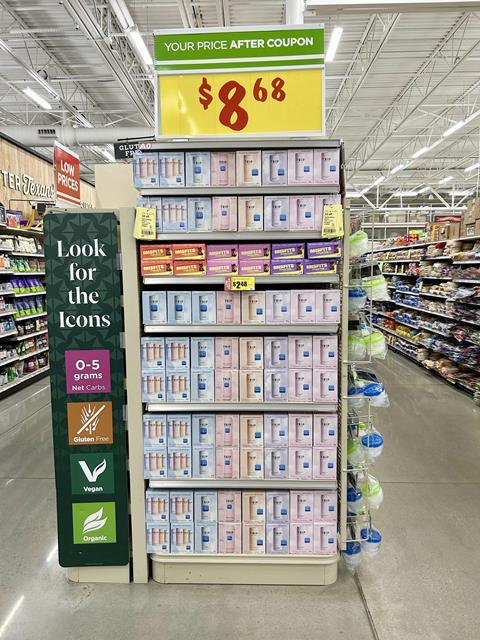
Whole Foods and Sprouts are particularly important for getting a toehold in the US, rewarding story, provenance and quality over price, much like Waitrose in the UK. Both operate from around 500 stores, with Sprouts aiming to triple its estate longer term. Whole Foods is the benchmark premium grocer for imported better-for-you suppliers and carries a prestige and built-in international foods audience, but its central buying process is “rigorous and slow”, Wilson says, whereas Sprouts is more accessible for emerging brands.
The latter’s ‘Forager Program’ provides a three-month trial window across all its stores for brands to prove themselves, giving dedicated and highly visible shelf space as well as a chance for a permanent listing for those who make the grade, such as Milliways, which impressed buyers in just a few weeks.
“We’re one of the fastest brands to ever graduate in Sprouts,” Raviv says. “What’s great about the Forager scheme as a new brand is you know you’re not going to overinvest because it’s just a set three-month trial. You know exactly how much you need to produce for the trial and if it doesn’t work out the downside is quite limited.”
Power of the internet
DTC and social media have also levelled the playing field, presenting scrappy challengers with more affordable routes to market. Fletcher was a pioneer of taking a UK brand direct to consumer in the States with Graze. He says it’s still a great way to test a market, build awareness and scale before a retail launch.
Meal replacement brand Huel did just that in 2017 and grew sales to top $100m by 2025. The US can be a graveyard, CEO James McMaster points out, but going online makes it more of an educated play.
“For a two-year-old business, it was quite a ballsy bet,” he says. “But at the time it didn’t feel that way because the UK was flying. We sorted production with a co-packer and created an office in LA with about five employees and launched Huel.com. It was also less of a gamble than going the retail route, as we could control costs better. After that, it just blew up really quickly.”
Trip has leaned on the reach of social media and digital selling through DTC and TikTok to drive awareness as well as sales. Its founders are acutely conscious of how the power of word of mouth has been amplified in the modern world by influencers. The reach of the brand’s legion of celebrity ambassadors and investors – in the US and globally – is astounding, significantly boosted just this week by a partnership with Kendall Jenner. The Kardashians star will promote Trip to her 277 million Instagram followers and front a marketing campaign including billboards in Times Square and Hollywood.
Jenner joins singer and actor Joe Jonas (12.5 million followers on Instagram), Victoria’s Secret model Alessandra Ambrosio (11.7 million), stars of The Vampire Diaries Paul Wesley (13.6 million) and Ian Somerhalder (26.3 million), and model and TV presenter Ashley Graham (20.6 million) on the Trip roster of big-name shareholders and influencers.
Ferdi notes US retailers place real value on the strength of a brand’s community, both on social media and in real life. “Trip is recognised by US retailers as a powerhouse on TikTok and Instagram,” she says. “What has historically been one of the toughest retail environments to break into has instead become one where Trip has thrived, thanks to the global social community the brand brings with it.”
Birrell reckons UK fmcg brands can take heart from the current generation of challengers proving the rewards of a US push can outweigh the risks. “I’ve spent my whole career in the US, and I love it, but it gave me more sleepless nights than any other market in the world. It’s hard and it does have this reputation as a graveyard for UK brands. But I don’t think that’s true. Lots of brands have made it work.”
No comments yet